Society & Finance
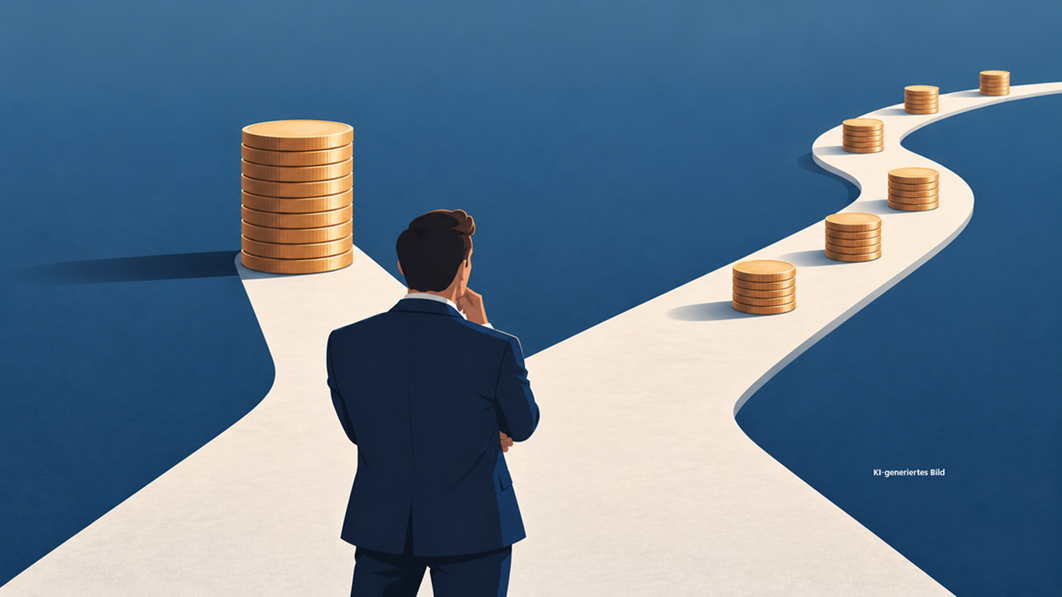
When a fixed-term deposit matures, a retirement product pays out, a property is sold or an inheritance is received, investors face the question of what to do with the newly available capital. Should they invest the entire amount immediately? Or should they proceed more cautiously and enter the market gradually? After all, prices might soon fall, making it possible to invest at more attractive levels by waiting. Perhaps a market crash is even imminent because the AI bubble is about to burst, oil prices are weighing on the economy or rising interest rates are affecting equity markets.
Many investors choose a gradual approach in such situations, spreading their investment over an extended period. This reduces their dependence on a single entry price. At the same time, they may miss interim market gains because part of their capital remains on the sidelines. This strategy is known as cost averaging, phased investing or, colloquially, the drip-feed investing. The alternative is a lump sum investment of the entire amount.
Lump Sum Investment or Cost Averaging?
In this article, we examine which of the two strategies has performed better historically. We consider an investor who invests an amount in the equity market either immediately in full or in ten equal instalments over ten months. Investment performance is measured using the MSCI World equity index. Initially, we also assume that uninvested capital earns no interest and exclude transaction costs.
If the entire amount is invested immediately, its value develops in line with the MSCI World Index over the following months. Under cost averaging, however, only one tenth of the investment participates in the performance of the MSCI World in the first month, while 90 percent remains uninvested and earns no interest. At the beginning of the second month, another tenth is added, meaning that 20 percent of the total amount now participates in the performance of the MSCI World, while the remaining 80 percent does not. This continues until the final instalment is invested at the beginning of the tenth month.
Once the final instalment has been invested, the performance of cost averaging and the lump sum investment differs only in their respective starting values from that point onward, as both are fully exposed to the MSCI World from the tenth month. To determine which strategy performs better, it is therefore sufficient to compare their performance during the investment phase. We consider all possible investment phases from January 1970 to September 2026, yielding 680 observations.
Waiting Means Forgoing Returns
Historically, the lump sum investment came out ahead in roughly three quarters of all observations. Figure 1 shows that, in monthly comparisons since January 1970, the lump sum investment generated a higher return than cost averaging in 73 percent of cases. Cost averaging performed better in only 27 percent of cases.

Investors who chose cost averaging accepted lower returns on average. Over a ten-month investment period, the average return differential between the strategies was 5.1 percent. The longer the investment period, the greater these opportunity costs for investors.
Figure 2 shows the average return differential as a function of the length of the investment period. Spreading an investment over just two months already comes at a return cost, albeit only 0.5 percent. Over five months, the differential rises to 2.2 percent, and over ten months to the aforementioned 5.1 percent. For a period of two years, or 24 months, the average return differential reaches as much as 14.5 percent.

This raises the question of whether the starting points at which cost averaging performed better are randomly distributed or concentrated in particular market phases. Figure 3 shows that, for a ten-month investment period, the starting points at which cost averaging outperformed occur in clusters. The prolonged bear market following the bursting of the dot-com bubble and the financial crisis stand out. Investors who committed the entire amount in August 2008 performed around 20 percent worse than those who opted for cost averaging over ten months. However, cost averaging did not prevent an overall loss in that case either. Otherwise, periods in which the lump sum investment was superior predominate, often with a return advantage exceeding 20 percent.

While analysing past performance is straightforward, investors face the difficulty of not knowing whether a prolonged bear market might lie ahead. They can try to predict a bear market using risk indicators. High equity market volatility, measured by 200-day volatility, signals substantial price fluctuations and therefore risk. An inverted yield curve, in which a ten-year US Treasury bond yields less than a three-month Treasury security, is regarded as a potential warning sign of recession.
Figure 4 shows that the lump sum investment was statistically superior both during periods of high equity market volatility and when the US bond market yield curve was inverted. Even with more sophisticated measures, predicting bear markets generally remains unsuccessful.

So far, this analysis has excluded transaction costs and potential interest income on uninvested portions of the capital. Transaction costs reduce the return from cost averaging because each instalment incurs additional costs. Conversely, interest earned on capital that has not yet been invested can increase the return from cost averaging. Historically, transaction costs in Germany averaged 1 percent per transaction. Capital held in current accounts or fixed-term deposits earned an average of 0.3 percent per month. Over a ten-month investment period, the two effects roughly offset each other and therefore barely change the outcome of the return comparison.
Why Investors Still Prefer Cost Averaging
Given these results, the popularity of cost averaging among investors may initially seem surprising. Constantinides (1979) established this statistical finding almost 50 years ago. Why, then, do investors still frequently choose cost averaging?
Behavioural economics offers an answer through the concept of regret aversion (Loomes und Sugden, 1982). Investors want to avoid regretting a decision in hindsight. Anyone who invests their entire capital immediately before even a small market decline may be frustrated by the unfortunate entry point. With cost averaging, this regret is less pronounced because part of the capital can still be invested at lower prices. Falling prices may thus even be perceived as an opportunity. Statman (1995) describes how such psychological considerations can explain the popularity of phased investing. Cost averaging gives investors the feeling that they can better control the risk of entering the market at an unfavourable time.
Another explanation is loss aversion. Investors generally feel losses more acutely than gains of the same magnitude (Kahneman and Tversky, 1979). Those who invest their entire capital at once are immediately exposed to the risk of a loss. With cost averaging, by contrast, only part of the capital is initially exposed to market fluctuations. If prices fall, the absolute loss is smaller.
From the perspective of an individual investor, however, choosing cost averaging is not necessarily irrational. Ludwig von Mises (1949) emphasised that economic action is based on individual values. What is the best decision for one investor needs not be the best for another. Although the lump sum investment is superior in terms of expected returns, cost averaging can reduce perceived risk and concern about entering the market at an unfavourable time.
Returns Are Not Everything: Peace of Mind Comes at a Price
The historical analysis clearly favours the lump sum investment. Investors who commit available capital immediately achieve higher returns on average than those who spread their entry over several months.
Nevertheless, the statistical superiority of the lump sum investment does not translate into a universally applicable recommendation. Investors differ in their perception of risk and their willingness to tolerate temporary losses. Those who reduce their concern about an immediate market decline by investing gradually may derive subjective benefits from doing so and probably sleep better at night as a result. And investors should be allowed a good night’s sleep.
Short Interview with Dr Philipp Immenkötter
1. What is the difference between investing a lump sum and investing gradually?
Philipp Immenkötter: Lump-sum investing means putting all available capital into the stock market immediately. Gradual investing spreads the investment over several months. This reduces dependence on a single entry point. However, investors may miss out on market gains while some of their money remains uninvested. Both approaches therefore involve different risks and opportunities.
2. Which investment strategy has performed better historically?
Immenkötter: Our analysis of the MSCI World from January 1970 to September 2026 shows that lump-sum investing performed better in 73 per cent of the periods examined. Gradual investing outperformed in only 27 per cent. Investors who spread their investment over ten months achieved returns that were, on average, 5.1 per cent lower than those who invested immediately.
3. When can investing gradually be a better option?
Immenkötter: Gradual investing can be advantageous during prolonged periods of falling share prices. During the 2008 financial crisis, for example, this approach performed considerably better. However, investors still suffered losses. As such market downturns are difficult to predict reliably, investing a lump sum remains statistically the more successful strategy over time.
4. Why do many investors still prefer to invest gradually?
Immenkötter: Many investors worry about investing all their money just before share prices fall. By investing gradually, they can buy shares at lower prices if markets decline. This reduces the fear of making a poor decision. Although this approach tends to produce lower returns on average, it can provide greater peace of mind and help investors sleep better at night.
5. Which data and academic research underpin the analysis?
Immenkötter: Our calculations use historical MSCI World data and additional market information from LSEG. We also draw on academic research by Constantinides on gradual investing, alongside studies by Kahneman and Tversky and Loomes and Sugden examining how people make decisions under uncertainty.
References
Constantinides, George M. (1979): A Note on the Suboptimality of Dollar-Cost Averaging as an Investment Policy. Journal of Financial and Quantitative Analysis 14 (2), 443–450. Available at: doi.org/10.2307/2330513 (accessed 15 October 2026).https://doi.org/10.2307/2330513
Kahneman, Daniel / Tversky, Amos (1979): Prospect Theory: An Analysis of Decision under Risk. Econometrica 47 (2), 263–292. Available at: www.jstor.org/stable/1914185 (accessed 15 October 2026).https://www.jstor.org/stable/1914185
Loomes, Graham / Sugden, Robert (1982): Regret Theory: An Alternative Theory of Rational Choice Under Uncertainty. The Economic Journal 92 (368), 805–824. Available at: doi.org/10.2307/2232669 (accessed 15 October 2026).https://doi.org/10.2307/2232669
Mises, Ludwig von (1949): Human Action: A Treatise on Economics. New Haven: Yale University Press. Available at: mises.org/library/book/human-action (accessed 15 October 2026).https://mises.org/library/book/human-action
Statman, Meir (1995): A Behavioral Framework for Dollar-Cost Averaging. The Journal of Portfolio Management 22 (1), 70–78. Available at: doi.org/10.3905/jpm.1995.409537 (accessed 15 October 2026).https://doi.org/10.3905/jpm.1995.409537
About the author
Senior Research Analyst. Graduate in Mathematical Economics, PhD in Finance from the University of Cologne, the University of Pittsburgh and the University of Trier. Expertise in capital markets, inflation, subsidies and share buybacks.
Legal notice
The information contained and opinions expressed in this document reflect the views of the author at the time of publication and are subject to change without prior notice. Forward-looking statements reflect the judgement and future expectations of the author. The opinions and expectations found in this document may differ from estimations found in other documents of Flossbach von Storch SE. The above information is provided for informational purposes only and without any obligation, whether contractual or otherwise. This document does not constitute an offer to sell, purchase or subscribe to securities or other assets. The information and estimates contained herein do not constitute investment advice or any other form of recommendation. All information has been compiled with care. However, no guarantee is given as to the accuracy and completeness of information and no liability is accepted. Past performance is not a reliable indicator of future performance. All authorial rights and other rights, titles and claims (including copyrights, brands, patents, intellectual property rights and other rights) to, for and from all the information in this publication are subject, without restriction, to the applicable provisions and property rights of the registered owners. You do not acquire any rights to the contents. Copyright for contents created and published by Flossbach von Storch SE remains solely with Flossbach von Storch SE. Such content may not be reproduced or used in full or in part without the written approval of Flossbach von Storch SE.
Reprinting or making the content publicly available – in particular by including it in third-party websites – together with reproduction on data storage devices of any kind requires the prior written consent of Flossbach von Storch SE.
© 2024 Flossbach von Storch. All rights reserved.